























For most of the past two years, the story investors wanted to hear about artificial intelligence was one of boundless demand: more chips, more power, more concrete poured for the warehouses full of servers that train and run the models. This week served up a blunter, more complicated version of that story, and it played out partly on home soil.
Buried in a busy trading session that also saw retailers Bunnings and JB Hi-Fi sound caution on consumer spending, the Australian Financial Review reported that the Australian Securities and Investments Commission is examining the failure of Firmus, one of the local names that had attached itself to the global rush to build AI computing capacity. On the same day, markets were digesting a very different signal from the other end of the industry, as Alphabet delivered quarterly results that showcased just how much money its AI and cloud businesses are now generating.
The juxtaposition is the point. One company’s collapse and one giant’s blockbuster numbers, reported side by side, capture the two-speed reality of the AI build-out as it matures from hype into hard commercial accounting.
What the regulator is looking at
Firmus belongs to a cohort of infrastructure players that pitched themselves as suppliers of the picks and shovels for the AI gold rush: the data centre space, the high-density cooling and the fleets of graphics processing units that AI workloads devour. These businesses promised to sit between the hyperscalers and the energy grid, monetising the scarcity of compute.
According to the AFR’s reporting, ASIC is now scrutinising how the venture came undone. Regulatory interest of this kind typically centres on questions that matter to anyone who put money in or extended credit: whether the company’s financial position was accurately represented, whether directors met their obligations as the business ran into trouble, and whether creditors and investors were treated appropriately in the lead-up to failure. FluentSea has not independently verified the detail of the probe, and ASIC examinations do not imply that any wrongdoing has been established.
What is clear is the symbolism. The collapse of a company that wrapped itself in the AI infrastructure narrative, now under the regulator’s eye, is a reminder that a compelling thematic does not guarantee a viable balance sheet. Building and operating data centres is a capital-hungry, long-dated business in which the gap between a signed intention and paid-up, utilised capacity can sink an undercapitalised operator.
The other side of the ledger
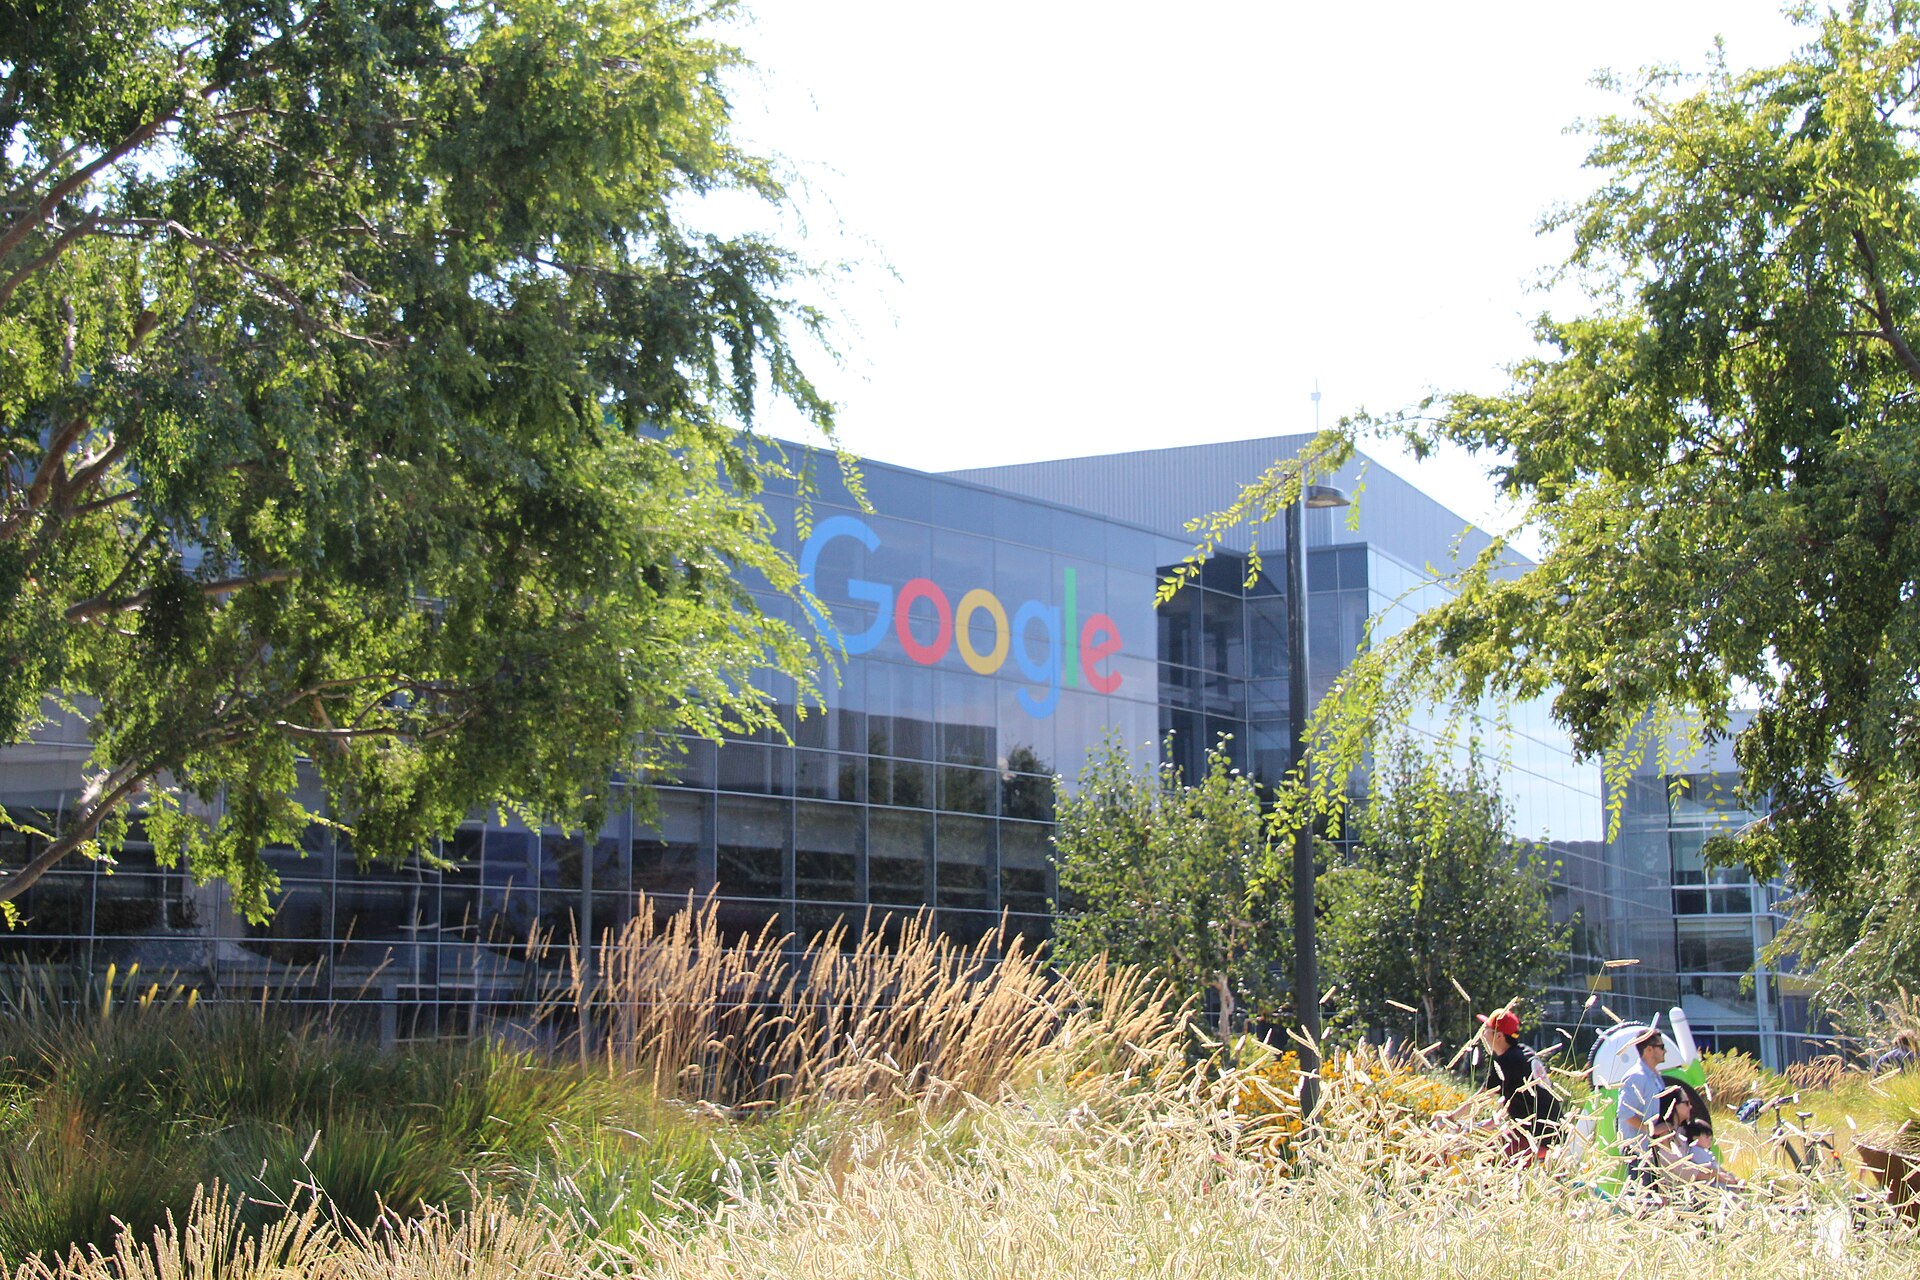
The optimists have plenty to point to, and Alphabet handed them a fresh exhibit. The parent of Google reported results that underlined how AI is translating into revenue at the top of the market, with its cloud division and advertising engine both benefiting from the technology. The irony of the session was that Alphabet’s share price fell anyway, a move that says as much about lofty expectations and the broader nerves around richly valued tech stocks as it does about the company’s performance.
That tension runs through the whole sector. Bulls argue that demand for AI compute is real, durable and still only partly met, which is precisely why the hyperscalers keep lifting their capital spending forecasts. Sceptics counter that a boom funded by enormous upfront investment, much of it in rapidly depreciating hardware, is vulnerable to any wobble in demand or financing, and that the weaker players will be exposed first. A regulator picking through the wreckage of a failed Australian infrastructure outfit on the same day a trillion-dollar company posts AI-driven profits is a neat illustration of both arguments being true at once.
There is a sober historical rhyme here. Previous technology build-outs, from railways to fibre-optic cable in the dotcom era, produced genuinely transformative infrastructure and a long list of casualties among the companies that financed it too aggressively or too early. The capacity often outlasts the balance sheets that created it.
Why it matters for Australia
For Australia, the Firmus episode lands at a delicate moment. Governments at both state and federal level have been courting data centre investment as a pillar of economic strategy, pitching cheap land, renewable energy and political stability to global operators weighing where to put their next gigawatt of capacity. The sector has become a fixture of FluentSea’s coverage, from off-grid campuses in Western Australia to board renewal at the listed heavyweights. The promise is jobs, exports of digital services and a seat at the table of a strategically important industry.
A local failure complicates that pitch, and not only for the investors directly affected. It raises fair questions about how carefully some of these ventures were capitalised, how realistic their demand assumptions were, and whether the enthusiasm of the moment outpaced the discipline the projects required. For superannuation funds, lenders and retail investors who have been encouraged to gain exposure to the AI theme, it is a reminder that the infrastructure layer carries its own distinct risks, separate from the fortunes of the chipmakers and the model developers that dominate the headlines.
It also hands ASIC a live test case. How the regulator handles the failure of an AI-badged company will signal how closely it intends to police a space where ambitious claims, speculative capital and genuine technological change are tangled together. Clear enforcement where it is warranted would help separate credible operators from those riding the narrative, which is in the long-term interest of the serious players trying to build Australia’s compute capacity.
What’s next
Expect the detail of the Firmus collapse to emerge slowly, through administrators’ reports, creditor processes and whatever ASIC chooses to make public as its examination proceeds. The broader market signal is likely to be quicker and louder: investors are increasingly demanding that AI infrastructure businesses show real, paying utilisation rather than announced intentions, and they are discriminating between the well-funded and the fragile.
For Australian policymakers chasing data centre investment, the lesson is to welcome the capital while scrutinising the capital structure. The AI compute story is far from over, and on the evidence of Alphabet’s numbers the demand is real. But as Firmus shows, being on the right side of a megatrend is not the same as surviving it.
Sources: Australian Financial Review, Markets.